
 By

JOHANNESBURG — Integrated mobility solutions provider Zeda Limited (JSE: ZED) has demonstrated notable operational resilience, delivering double-digit earnings growth for the half-year ended 31 March 2025.
Despite navigating a highly constrained revenue environment and broader macroeconomic pressures across sub-Saharan Africa, the Group’s diversified product architecture and stringent cost discipline successfully shielded its bottom line.
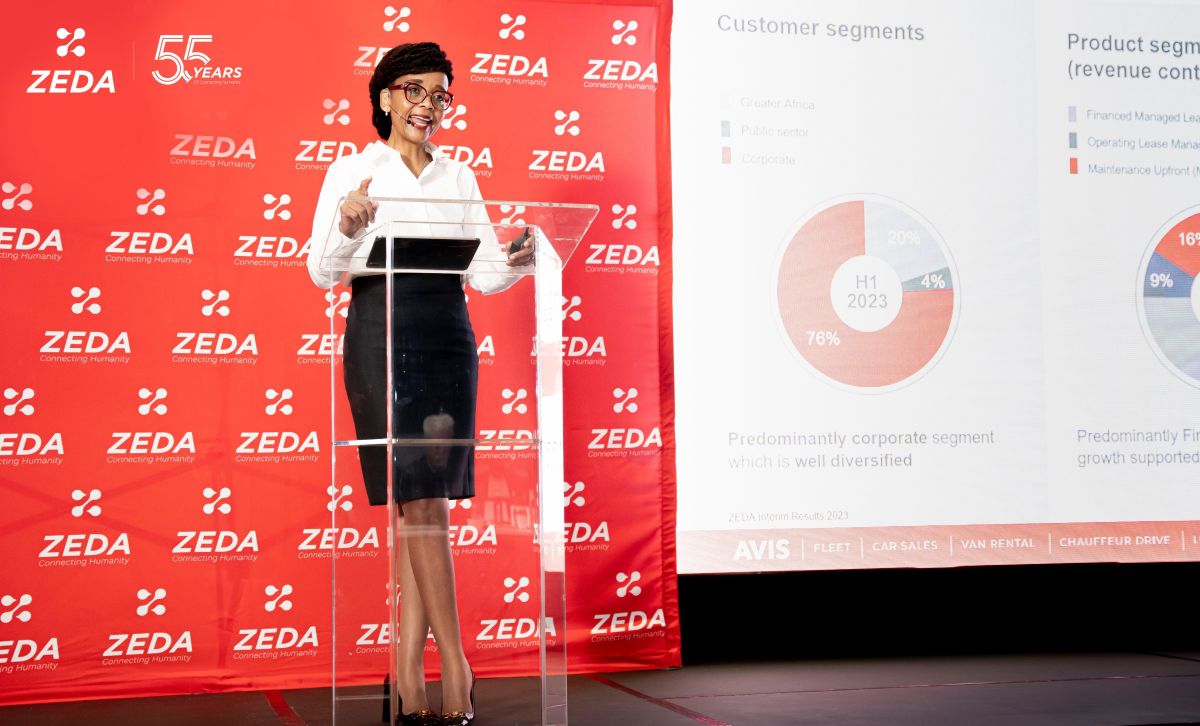
Group Chief Executive Officer Ramasela Ganda attributed the solid interim performance to the strict execution of Zeda’s core strategic playbook: “financing right, buying right, using right, and disposing right”.
“This reaffirms the strength of our robust operating model, our diversified portfolio, and disciplined strategy execution,” Ganda stated. “In a period where traditional car rental and vehicle sales faced mounting pressure, our Leasing, Subscription, and Greater Africa strategies delivered, helping grow earnings, improve margins, and continue investing for the long term.”
Financial Metrics at a Glance
Zeda’s headline numbers reflect a business successfully optimizing its existing asset base to squeeze out higher efficiencies:
- Group Revenue: Stable at R5.2 billion.
- EBITDA Margin: Resiliently maintained at a robust 34%.
- Operating Profit: Up 5.4% to yield a superior operating margin of 16%, marking a 100-basis-point expansion.
- Earnings Growth: Headline Earnings Per Share (HEPS) grew by 11.2%, while Basic Earnings Per Share (BEPS) advanced 11.1%.
- Capital Returns: Return on Investment Capital (ROIC) landed at 12.2%, tracking safely above the Group’s Weighted Average Cost of Capital (WACC) of 11.8%. Return on Equity (ROE) remained a solid 21.8%.
- Shareholder Returns: The Board declared an interim dividend of 55 cents per share, representing a 10% year-on-year growth.
To bolster its capital structure, Zeda also registered its Domestic Medium-Term Note (DMTN) program with the JSE, successfully executing its first bond issuance of R850 million in March 2025. Concurrently, the Group noted progress on its sustainability mandates, reporting a reduction in scope 1 and 2 carbon emissions.
Leasing and Greater Africa Anchor Performance
The Group’s leasing business segment emerged as a key growth driver, with revenue increasing 5.6% to R1,414 million. Performance in this division was underpinned by aggressive corporate penetration, heavy commercial fleet expansions, and cross-border gains.
In particular, the heavy commercial segment continues to act as a crucial growth pillar, supported by a healthy order book. The heavy commercial fleet grew by 31% during the period, now accounting for 15% of total leasing revenue.
Beyond South Africa’s borders, the “Greater Africa” regional strategy yielded impressive dividends. The segment posted a 6% increase in revenue and a substantial 15% surge in operating profit, fuelled primarily by strong operational performances in Zambia, Namibia, and Lesotho.
Rental Dynamics: Subscription Surges Amid Insurance Slump
While overall rental days crept up by 2.5%, the underlying metrics reveal a structural shift in consumer behavior and market dynamics. Zeda recorded a massive 49% surge in its short-term subscription business. Management credited this exponential growth to recent technology upgrades that drastically simplified transaction processes for retail customers.
However, this structural boom was heavily offset by cyclical contractions in the replacement and inbound car rental segments. The insurance replacement business faced severe compression due to uncharacteristically low claims rates across the broader insurance industry, coupled with a decreasing number of policyholders opting for car rental extensions.
To counter these volume pressures, Zeda turned its focus inward toward fleet optimization. By lowering damage incidents, shortening turnaround times on out-of-service vehicles, and dynamically shifting fleets between regions, the Group successfully pushed its fleet utilization rate up from 72% to 75%.
Forward Outlook and Cost Mitigation
Looking ahead, Zeda’s executive leadership emphasized that the core corporate strategy remains unchanged. The Group will continue to anchor its long-term growth on four distinct structural pillars: the subscription business, the corporate leasing book, the Greater Africa portfolio, and its used car disposal channels.
However, acknowledging persistent regional headwinds, Ganda indicated that the immediate focus will pivot toward aggressive margin preservation.
“We will prioritize efficiencies to contain our operating costs below inflation,” Ganda concluded. “We are also implementing a multi-year efficiency programme that aligns with our portfolio review to enhance the performance of our services and improve branch profitability.”