 By
Johannesburg — South Africa’s maiden push to integrate large-scale gas-to-power into its national grid has hit a major structural roadblock. Minister of Electricity and Energy Dr. Kgosientsho Ramokgopa announced the conclusion of Bid Window 1 (BW1) of the Gas Independent Power Producer Procurement Programme (GASIPPPP), revealing that no preferred bidders were appointed and zero generation capacity was awarded.
The outcome underscores the complex operational and fuel-security headwinds confronting South Africa’s nascent gas economy, even as policymakers insist that the country’s long-term energy transition remains anchored to gas as a critical flexibility and base-load bridge.
The Anatomy of the Stalling: Fuel Supply Realities
GASIPPPP Bid Window 1 was designed to procure 2,000 megawatts (MW) of generation capacity, aligning with the strategic imperatives outlined in the Integrated Resource Plan. When the submission window closed on 29 May 2026, the Independent Power Producer (IPP) Office had received four bids collectively offering 2,830 MW—a signal of robust private sector appetite.
However, stringent structural requirements ultimately tripped up the process. The Request for Proposals (RFP) mandated that bidders provide ironclad assurances of a secure gas supply. In practice, this proved to be an insurmountable hurdle.
South Africa currently imports the vast majority of its natural gas feedstock from neighbouring Mozambique and operates without a dedicated Liquefied Natural Gas (LNG) receiving terminal.
Because bidders could not furnish the high level of fuel-supply certainty demanded by the RFP framework, none of the submissions satisfied the mandatory functional criteria, forcing the Department of Electricity and Energy to draw the line without making any awards.
A Pragmatic Pivot Toward Bid Window 1.5
Rather than viewing the outcome as a policy failure, energy economists and government officials are framing the conclusion of BW1 as a vital diagnostic exercise. As South Africa pioneers complex gas-to-power procurement on the continent, the process has exposed critical structural interdependencies between commercial requirements, technical feasibility, fuel-supply logistics, and enabling infrastructure.
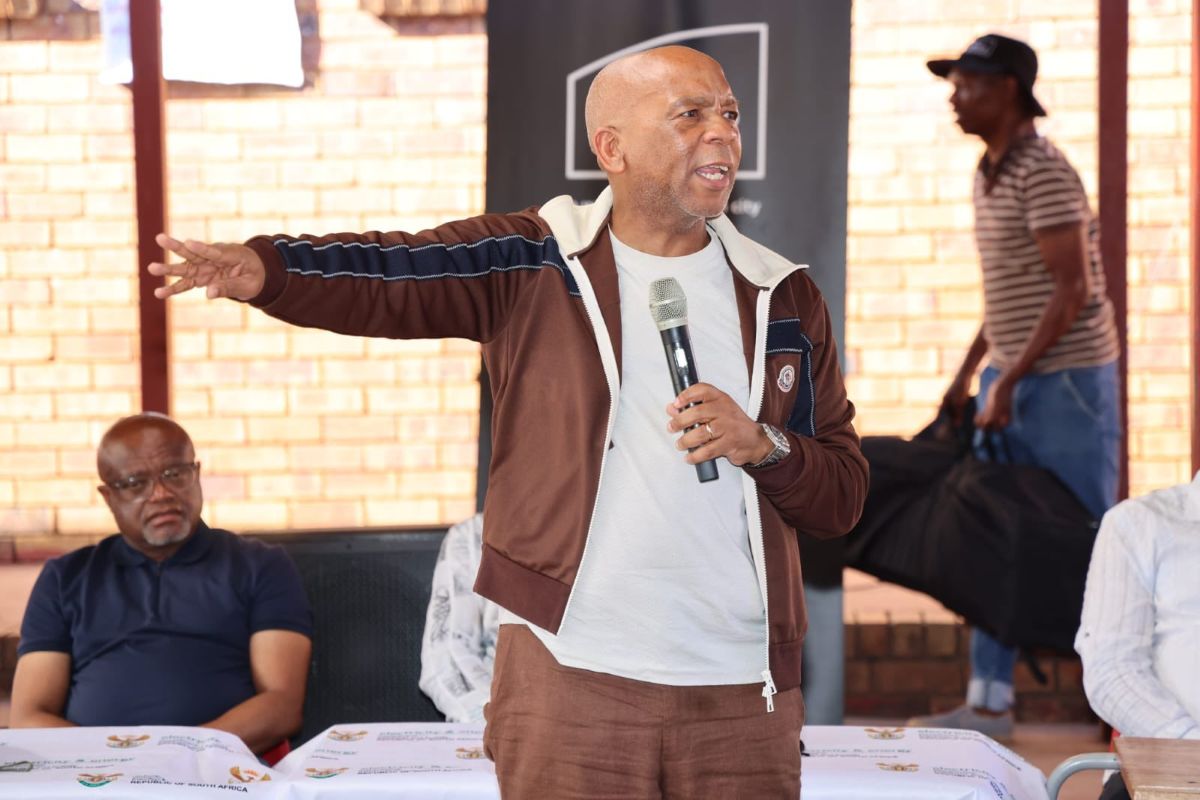
Reaffirming the state’s long-term commitment, Minister Ramokgopa emphasized that South Africa is not backing away from its strategic trajectory:
“South Africa is not retreating from our gas-to-power objectives. As the first in Africa to take on this ambition, we are further enabled by this first procurement process to strengthen the conditions necessary to achieve them. Our responsibility now is to address the infrastructure, commercial and institutional conditions required to translate market interest into viable and deliverable projects.”
The lessons learned from BW1 are expected to serve as a blueprint for refining subsequent iterations, including an anticipated structural pivot toward a more viable “Bid Window 1.5.” Addressing the missing link—specifically, accelerating domestic and imported gas infrastructure like LNG terminal development—will be central to unlocking private capital in future rounds.
Looking Ahead: The Path to Market Re-engagement
The Department of Electricity and Energy and the IPP Office have acknowledged the heavy capital, time, and human resources invested by project developers, original equipment manufacturers (OEMs), lenders, and terminal developers during BW1.
To maintain investor confidence, authorities plan to conduct structured stakeholder consultations to gather market intelligence before plotting the next phase.
Any future procurement rounds, alongside revised compliance requirements and updated timelines, will undergo rigorous statutory, governance, and procurement approvals. The Department has indicated that further communications regarding the roadmap for the gas programme will be released through official channels before the close of the calendar year.
For South Africa’s energy sector, the message is clear: while the road to a diversified energy mix is fraught with logistical and infrastructural friction, the integration of gas remains indispensable to grid adequacy, economic resilience, and long-term energy security.